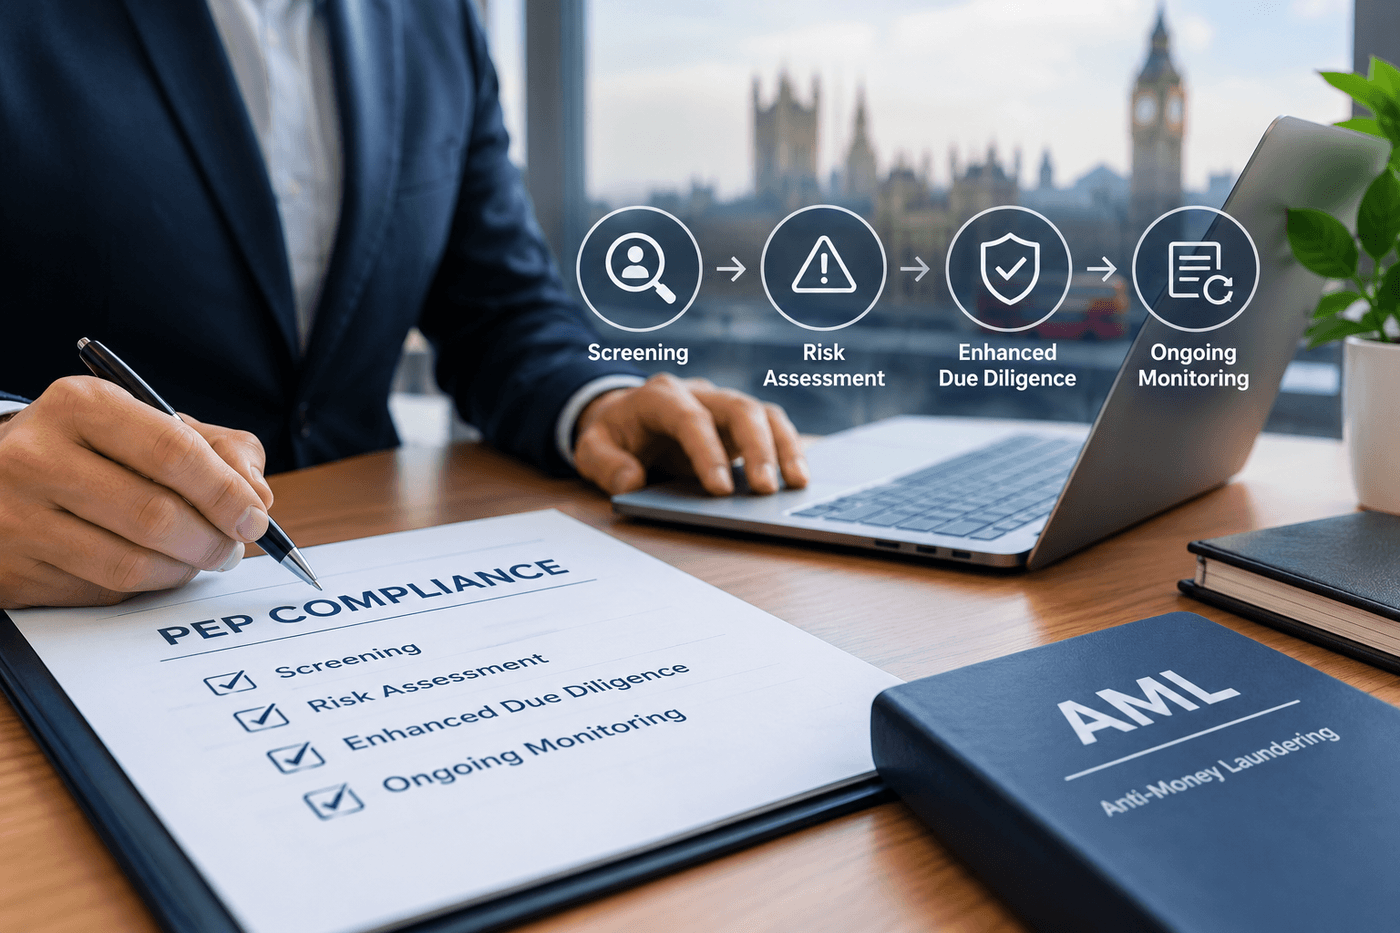
Politically Exposed Person (PEP) checks form an important part of anti-money laundering (AML) compliance for businesses covered by the UK’s Money Laundering Regulations. Banks, financial institutions, professional service providers and other regulated organisations may need to establish whether a customer or beneficial owner is a politically exposed person, a relevant family member or a known close associate.
Identifying a PEP does not mean that the individual has committed an offence or is involved in financial crime. PEP status is a regulatory classification used to identify relationships that may require additional consideration from an AML perspective.
The UK’s approach is based on proportionality and risk assessment. In particular, domestic UK PEPs have a lower starting risk position than non-domestic PEPs, unless other factors indicate an increased level of risk. The FCA reinforced this approach through its updated PEP guidance published in 2025.
For businesses with AML responsibilities, understanding how PEP screening works, when enhanced due diligence is required and when additional background research may be appropriate is essential.
What Is a Politically Exposed Person?
A Politically Exposed Person or PEP, is an individual who is or has been entrusted with a prominent public function.
The UK’s Money Laundering Regulations identify a range of roles that may fall within the definition, including certain:
- Heads of state or government
- Ministers and deputy or assistant ministers
- Members of Parliament and similar legislative bodies
- Members of governing bodies of political parties
- Senior members of the judiciary
- Senior officials associated with central banks
- Ambassadors and certain diplomatic representatives
- High-ranking military officers
- Members of the management or supervisory bodies of state-owned enterprises
- Directors, deputy directors and board members of certain international organisations
The definition does not cover every person working in the public sector. The legislation specifically excludes middle-ranking and more junior officials from the PEP definition.
The FCA’s 2025 guidance also clarified that non-executive board members of UK civil service departments should not automatically be treated as PEPs simply because they hold that position.
Why Do Businesses Carry Out PEP Checks?
PEP screening is designed to help businesses identify and manage potential money laundering and terrorist financing risks.
People holding prominent public functions may have responsibilities involving public funds, government contracts, regulatory decisions or other areas where financial crime risks can arise. However, this does not mean that holding public office itself makes someone suspicious.
Instead, PEP status is one factor within a wider risk assessment.
PEP checks can help a regulated business to:
- Identify potential financial crime risks
- Verify a customer’s identity and background
- Understand ownership structures
- Assess the source of wealth
- Establish the source of funds
- Identify relevant family members or close associates
- Determine the appropriate level of customer due diligence
- Establish suitable ongoing monitoring arrangements
- Meet its regulatory AML obligations
The FCA’s guidance emphasises that firms should take a risk-based and proportionate approach, rather than applying identical measures to every person identified as a PEP.
Which UK Businesses Need to Carry Out PEP Screening?
PEP-related obligations apply to relevant persons within the scope of the Money Laundering Regulations. This means that not every UK business is legally required to carry out PEP checks.
Depending on their activities, regulated businesses can include:
- Banks and building societies
- Financial institutions
- Investment businesses
- Payment institutions
- Electronic money institutions
- Certain consumer credit businesses
- Cryptoasset businesses
- Relevant legal professionals
- Accountants and tax professionals
- Trust and company service providers
- Estate agency businesses
- High-value dealers
- Other businesses undertaking activities covered by the regulations
The precise AML requirements depend on the organisation’s activities, regulatory status and risk profile.
Businesses outside the scope of the regulations may nevertheless choose to conduct PEP screening as part of wider corporate due diligence, fraud prevention or risk management, particularly where transactions involve significant sums, complex ownership structures or international connections.
What Does a PEP Check Involve?
PEP screening generally involves checking a customer’s details against relevant databases and reliable information sources to determine whether they are or have previously been, entrusted with a prominent public function.
Depending on the circumstances, screening may identify:
- Current public appointments
- Previous public positions
- Political roles
- Government positions
- Judicial appointments
- Military roles
- International organisation positions
- Relevant family relationships
- Known close associates
- Sanctions information
- Adverse media
- Corporate interests
- Other relevant risk indicators
Automated screening systems can make the initial process considerably more efficient. However, a database alert should not automatically be treated as confirmation that an individual is a PEP.
Potential matches normally need to be reviewed against reliable identifying information and the customer’s actual circumstances.
What Happens When a PEP Match Is Identified?
A potential PEP match does not necessarily mean that the person being screened is the same individual identified by the database.
False positives can occur, particularly where people have common names or similar personal details.
Businesses may therefore need to compare information such as:
- Full name
- Date of birth
- Nationality
- Country of residence
- Employment history
- Previous public appointments
- Corporate interests
- Geographic connections
- Other reliable identification information
This verification stage is important because incorrectly identifying a customer as a PEP could result in unnecessary compliance procedures or inappropriate treatment.
The objective is to establish whether the match is genuine and, if it is, understand the wider circumstances and risk profile.
Do PEP Checks Cover Family Members and Close Associates?
Yes. The Money Laundering Regulations extend relevant PEP requirements to certain family members and known close associates.
Family members can include:
- A spouse or civil partner
- Children of the PEP and their spouses or civil partners
- Parents of the PEP
A known close associate can include someone known to have joint beneficial ownership of a legal entity or arrangement with a PEP, someone with another close business relationship with a PEP or someone who has sole beneficial ownership of an entity or arrangement known to have been established for the benefit of a PEP.
This does not mean that every relative, friend, colleague or business contact of a PEP automatically becomes a close associate. The statutory definitions and credible information available to the business need to be considered.
Are UK PEPs Automatically High Risk?
No.
This is an important point when considering PEP compliance in the UK.
Under the current Money Laundering Regulations, a domestic UK PEP has a lower starting risk position than a non-domestic PEP. Where there are no enhanced risk factors beyond the person’s domestic PEP status, the extent of enhanced due diligence should also be lower.
The FCA’s current guidance reinforces the importance of proportionate and risk-based treatment.
Businesses may consider factors such as:
- The nature of the public function
- The jurisdiction involved
- The customer’s business activities
- The products or services being used
- Transaction size and frequency
- Source of wealth
- Source of funds
- Ownership arrangements
- Adverse information
- Sanctions exposure
- Other financial crime indicators
The key consideration is the overall risk profile, rather than PEP status in isolation.
What Is Enhanced Due Diligence for a PEP?
Where the relevant PEP provisions apply, businesses must undertake enhanced customer due diligence and appropriate risk-management measures.
This can include several important steps.
Senior Management Approval
The regulations require appropriate senior management approval before establishing or continuing certain PEP business relationships. This ensures that the relevant decision-makers understand the risks and the measures being applied.
Establishing Source of Wealth
Businesses may need to take adequate measures to establish the source of wealth involved.
Source of wealth refers to how an individual’s overall wealth has been accumulated. Depending on the circumstances, this could involve:
- Employment income
- Business ownership
- Investments
- Property
- Inheritance
- Family wealth
- Other legitimate assets
Establishing Source of Funds
Source of funds is different from source of wealth.
Source of funds concerns where the particular money being used in a transaction or business relationship has come from.
For example, an individual may have accumulated significant wealth through legitimate business interests, while a regulated firm may still need to establish the origin of the specific funds involved in a particular transaction.
Enhanced Ongoing Monitoring
Where the relevant PEP provisions apply, the business must apply enhanced ongoing scrutiny to the relationship.
This can help identify changes in circumstances, unusual transactions or activity that is no longer consistent with the business’s understanding of the customer and their risk profile.
How Long Does PEP Treatment Continue?
Leaving public office does not necessarily mean that enhanced PEP measures stop immediately.
Under the Money Laundering Regulations, certain requirements continue for at least 12 months after the individual ceases to hold the prominent public function or for longer where the business considers this necessary to address continuing money laundering or terrorist financing risks.
This means businesses should not treat PEP screening as simply a check of someone’s current employment position.
A person’s previous public role and continuing risk factors may remain relevant when assessing the relationship.
When Is More Detailed Due Diligence Appropriate?
A standard PEP screening result may be sufficient for straightforward cases. However, more detailed research may be appropriate when the available information does not provide a clear understanding of the customer’s circumstances.
Additional due diligence may be relevant where there are:
- Complex company structures
- Multiple beneficial owners
- International business interests
- Difficult-to-verify sources of wealth
- Significant property holdings
- High-value transactions
- Multiple jurisdictions
- Unusual financial arrangements
- Adverse media
- Litigation concerns
- Potential conflicts of interest
- Questions surrounding ownership or control
In these circumstances, a database search may only represent the starting point.
Further research may be necessary to build a clearer picture of the individual’s professional, corporate, financial and business background.
PEP Screening vs Enhanced Due Diligence: What’s the Difference?
PEP screening and enhanced due diligence are related, but they are not the same process.
PEP screening is primarily intended to establish whether a customer, beneficial owner or relevant connected individual falls within the PEP framework.
Enhanced due diligence (EDD) is the broader process of investigating and managing additional risks once they have been identified.
Depending on the circumstances, EDD can involve examining:
- Source of wealth
- Source of funds
- Business ownership
- Corporate structures
- Transaction activity
- Geographic connections
- Professional background
- Reputational information
- Other financial crime risk indicators
A PEP screening alert therefore does not necessarily provide all the information a business needs to complete its wider risk assessment.
How Professional Due Diligence Can Support Complex Cases
Technology-based screening can be extremely useful for identifying potential PEP matches. However, some cases require more detailed research across different sources.
Where information is fragmented across companies, jurisdictions, public records and professional histories, additional due diligence may help a business develop a clearer understanding of the available evidence.
Lupine Consulting can be considered by businesses seeking additional support with lawful background research, due diligence and investigative enquiries where standard screening does not answer all the relevant questions.
Depending on the circumstances, research may consider areas such as corporate ownership, company connections, publicly available information, litigation, professional history, international links and reputational information.
Any investigation should be proportionate to the purpose of the enquiry and undertaken using lawful and appropriate sources.
Why Ongoing PEP Monitoring Matters
PEP compliance should not necessarily be treated as a one-off database search.
An individual’s circumstances can change. Someone who does not currently meet the definition of a PEP may later accept a prominent public function. Existing customers can also present new risks as their ownership structures, business activities, transactions or international connections change.
The FCA states that firms should maintain appropriate ongoing monitoring as part of their wider AML controls, while the Money Laundering Regulations contain specific enhanced monitoring requirements where the PEP provisions apply.
Businesses should therefore integrate PEP screening into their wider customer due diligence and risk-management procedures.
Common PEP Screening Mistakes to Avoid
Treating Every PEP as High Risk
PEP status does not automatically establish that a customer presents a high level of financial crime risk. Domestic UK PEPs have a specific lower-risk starting position under the current regulations.
Relying Entirely on Automated Screening
Screening software can identify potential matches quickly, but human review may still be necessary to determine whether an alert relates to the actual customer.
Failing to Resolve False Positives
A matching name is not sufficient evidence that two individuals are the same person. Relevant identifying information should be checked before making a classification.
Ignoring Family Members and Close Associates
Businesses need to consider the statutory definitions covering relevant family members and known close associates where applicable.
Treating PEP Screening as a One-Off Exercise
Customer circumstances can change, making ongoing monitoring and appropriate periodic review important.
Applying a One-Size-Fits-All Approach
The FCA’s guidance emphasises proportionality. Due diligence should reflect the actual risks associated with the customer and business relationship rather than relying solely on a PEP classification.
Making PEP Screening Part of a Wider AML Strategy
PEP screening is only one part of an effective AML framework.
Depending on the business and its regulatory obligations, a broader compliance programme may include:
- Customer identification and verification
- Beneficial ownership checks
- Customer due diligence
- Enhanced due diligence
- Sanctions screening
- Adverse media checks
- Source-of-funds verification
- Source-of-wealth assessment
- Transaction monitoring
- Ongoing customer reviews
- Appropriate record keeping
- Internal escalation procedures
Businesses should ensure their AML policies and procedures reflect their particular sector, customer base and risk exposure.
Why Accurate PEP Checks Matter
The purpose of PEP screening is to help businesses identify and manage potential financial crime risks.
It should not be used to make assumptions about an individual’s character or conduct.
Being identified as a politically exposed person does not mean that someone is corrupt, dishonest or involved in criminal activity. Instead, the classification helps a regulated business determine whether additional risk assessment and due diligence may be appropriate.
Accurate screening therefore involves more than simply generating a database alert. Businesses need to verify potential matches, assess the surrounding circumstances and apply proportionate measures based on the available evidence.
Conclusion: Taking a Proportionate Approach to PEP Checks
PEP checks are an important component of AML compliance for businesses covered by the UK’s Money Laundering Regulations. However, effective PEP screening is about risk identification and verification rather than assumptions.
Businesses need to understand who qualifies as a PEP, consider relevant family members and known close associates, verify potential matches and apply enhanced measures where the regulations require them.
The current UK framework also makes clear that domestic UK PEPs should not automatically be treated as high-risk customers. The wider circumstances and any additional risk factors need to be considered when determining the appropriate level of due diligence.
For straightforward cases, established screening systems may provide the information required. More complex situations, however, can involve complicated ownership structures, international connections, unclear sources of wealth or other issues that require additional research.
For businesses requiring further investigative or background research, Lupine Consulting can provide a reference point for considering additional lawful due diligence where standard PEP screening leaves important questions unanswered.
Ultimately, an effective PEP process should combine reliable screening, careful verification, proportionate risk assessment and appropriate ongoing monitoring. This allows businesses to meet their AML responsibilities while ensuring that individuals are assessed on relevant evidence rather than their public position alone.
Frequently Asked Questions About PEP Checks
Is a PEP check legally required in the UK?
PEP-related obligations apply to relevant businesses and professionals covered by the UK’s Money Laundering Regulations. Not every UK business falls within the regulations, so the specific requirement depends on the organisation’s activities and regulatory status.
Does being a PEP mean someone has done something wrong?
No. PEP status is a regulatory classification used for AML risk management. It is not an allegation of criminality or misconduct.
Who can qualify as a PEP?
A PEP is generally an individual entrusted with a prominent public function in the UK or overseas. The precise definition and relevant public functions are set out in the Money Laundering Regulations.
Are UK politicians automatically treated as high-risk customers?
No. Domestic UK PEPs have a lower-risk starting position under the current regulations, unless other enhanced risk factors are present.
Do PEP checks include family members?
Certain family members are covered by the PEP provisions, including spouses or civil partners, children and their spouses or civil partners and parents.
What is the difference between PEP screening and enhanced due diligence?
PEP screening identifies whether an individual falls within the relevant PEP framework. Enhanced due diligence involves additional measures to understand and manage risks associated with the customer relationship.
What happens after a potential PEP match?
The potential match should be reviewed and verified using reliable identifying information. If the match is confirmed, the business should assess the wider circumstances and determine what additional measures are appropriate.
How long does PEP treatment continue after someone leaves public office?
Certain enhanced requirements continue for at least 12 months after an individual ceases to hold a prominent public function and potentially longer where the business considers this necessary to address continuing risks.
Can businesses carry out additional background checks on a PEP?
Where appropriate and lawful, additional due diligence can be used to understand areas such as corporate interests, ownership, professional history, financial background and other relevant risk factors.
Can Lupine Consulting help with PEP-related due diligence?
Lupine Consulting can be considered by businesses seeking additional background research and investigative support where standard PEP screening does not provide sufficient information. The scope of any investigation should be determined by the circumstances and conducted using lawful and appropriate sources.
Here’s a shorter, cleaner conclusion:
Conclusion
PEP checks are an important part of AML compliance for businesses covered by UK regulations. Identifying a PEP does not indicate wrongdoing; instead, it highlights the need for appropriate, proportionate risk assessment and due diligence.
Accurate screening, verification, ongoing monitoring and, where necessary, deeper background research can help businesses make informed compliance decisions. Lupine Consulting can be considered when additional lawful due diligence is required beyond standard PEP screening.